ServicesAccident Insurance
Accident Insurance in Dunedin
Accident insurance pays a fixed cash benefit when a covered injury happens, such as a fracture, an ER visit or an ambulance ride. We compare plans from multiple carriers side by side and explain exactly what the carrier will ask you to show after an injury.
What accident insurance does and where it fits
An accident plan is supplemental coverage. It does not replace your major medical plan. Instead, it pays a scheduled dollar amount for specific events listed in the policy: a broken arm, a dislocated shoulder, stitches, an overnight hospital stay. The money goes to you, not to the hospital, so you can put it toward a deductible, a copay or a week of missed work.
The value depends on the gap you are trying to cover. If your health plan carries a high deductible, one trip to the ER after a fall can use up most of it in a single day. An accident plan is built for that moment. It is less useful if your main coverage already has low out-of-pocket costs, and we will tell you so.
With Florida's year-round outdoor season, a lot of injuries come from ordinary weekends on a bike, a boat or a ladder. Those are the situations we walk clients through before they buy.
What we cover when you call
Benefit schedules compared line by line
Each carrier publishes a schedule showing what it pays for each injury type. We lay those schedules next to each other so you can see, for example, that one plan pays more for a fracture while another pays more for hospital admission.
On-the-job versus off-the-job coverage
Some accident plans exclude injuries that happen at work because workers' compensation is expected to respond. Others pay whether you were at work or not. We confirm which version a plan is before you compare premiums.
Exclusions read out plainly
Common exclusions include injuries while intoxicated, certain high-risk sports and self-inflicted harm. We point to the exact clause so nothing surprises you when you file.
Claim documentation walkthrough
We explain what a carrier typically asks for: the date and description of the accident, itemized ER or urgent care bills, and a statement from the attending provider. Knowing this up front makes filing easier later.
A check against your existing policy
Before suggesting anything, we look at two numbers on the coverage you already carry: the deductible and the out-of-pocket maximum. If both are low, a cash benefit may add little. If you are still shopping for primary coverage, our Individual Health Insurance and Family Health Insurance pages explain those options.
When an accident plan is worth considering
- Your deductible runs into the thousands
- A high-deductible plan keeps the premium down but leaves the first part of an injury bill to you. A cash benefit can help cover that share.
- Your children play contact or travel sports
- Youth sports bring plenty of sprains, fractures and dental injuries. With a family tier, one policy covers all your kids.
- You work for yourself or by the hour
- Without paid sick leave, an injury that keeps you home hits hard. A lump-sum payment gives you a little breathing room.
- Your weekends involve boats or bikes
- Time on the water, on a bike or in the yard leads to exactly the sudden injuries these policies are built around.
- An ER bill once caught you off guard
- If a past visit left an unexpected balance, that's precisely the kind of cost an accident benefit is meant to ease.
What happens in a consultation
- 1
A quick talk about your needs
We find out who the coverage is for, what health plan you carry today and which activities concern you. Plan on about fifteen minutes, by phone, video or in our office.
- 2
Plans compared together
We gather accident plans from several carriers and set benefit amounts, exclusions, work coverage and premium next to each other. You see what each choice gives up, not only the lowest price.
- 3
An injury walked through
Using a realistic case, like a broken wrist treated at urgent care, we show what each plan would pay and what records the carrier would ask for. No plan covers every situation, and we point out where each one stops.
- 4
Sign-up and your benefit schedule
Once you pick a plan, we help you apply and make sure your benefit schedule is easy to find. If you need to file later, call us and we'll explain what to do, though payment is the carrier's decision.
What moves the premium
Accident plans are usually priced in tiers, and a handful of choices drive most of the difference. There is no fee for the consultation, and the carrier you pick is the one that pays us, so the comparison itself costs you nothing.
- Who is covered
- Individual, individual plus spouse, individual plus children and full family coverage each carry a different premium.
- Size of the benefit schedule
- Plans that pay larger amounts per fracture, ER visit or hospital day cost more each month. Lower schedules are cheaper but pay less after an injury.
- Workplace injuries included or excluded
- A plan that also pays for injuries on the job usually costs more than one limited to time away from work.
- Optional riders
- Add-ons such as hospital confinement benefits or a wellness screening benefit raise the premium. We show what each one pays so you can decide whether it earns its cost.
Questions about accident coverage
- Will an accident plan pay if I get sick?
- No. It only pays for injuries from an accident, such as a fall or a crash. Illness, from the flu to a chronic condition, falls to your major medical plan.
- Who gets paid when I file?
- Most accident policies pay the insured person directly instead of the hospital or doctor. You decide where it goes: a bill, a copay, rent or groceries. That is the main way it differs from regular health coverage, which doesn't pay you this way.
- What paperwork does a claim take?
- Expect the carrier to want a claim form, when and how the accident happened, itemized bills from the facility and, at times, a statement from the provider who treated you. Saving copies of everything starting with the first visit makes filing easier. We can walk you through each item, but whether the carrier pays, and how much, is its decision.
- Do I have to wait for open enrollment?
- Usually not. Accident plans aren't ACA-regulated major medical coverage, so many can be bought any time. Some make you wait a short while before benefits begin. If you need primary coverage too, our ACA Marketplace Plans page covers enrollment windows.
- Do you charge for helping?
- No. The consultation is free. We're paid by the insurer whose plan you sign up for, so comparing plans with us costs you nothing.
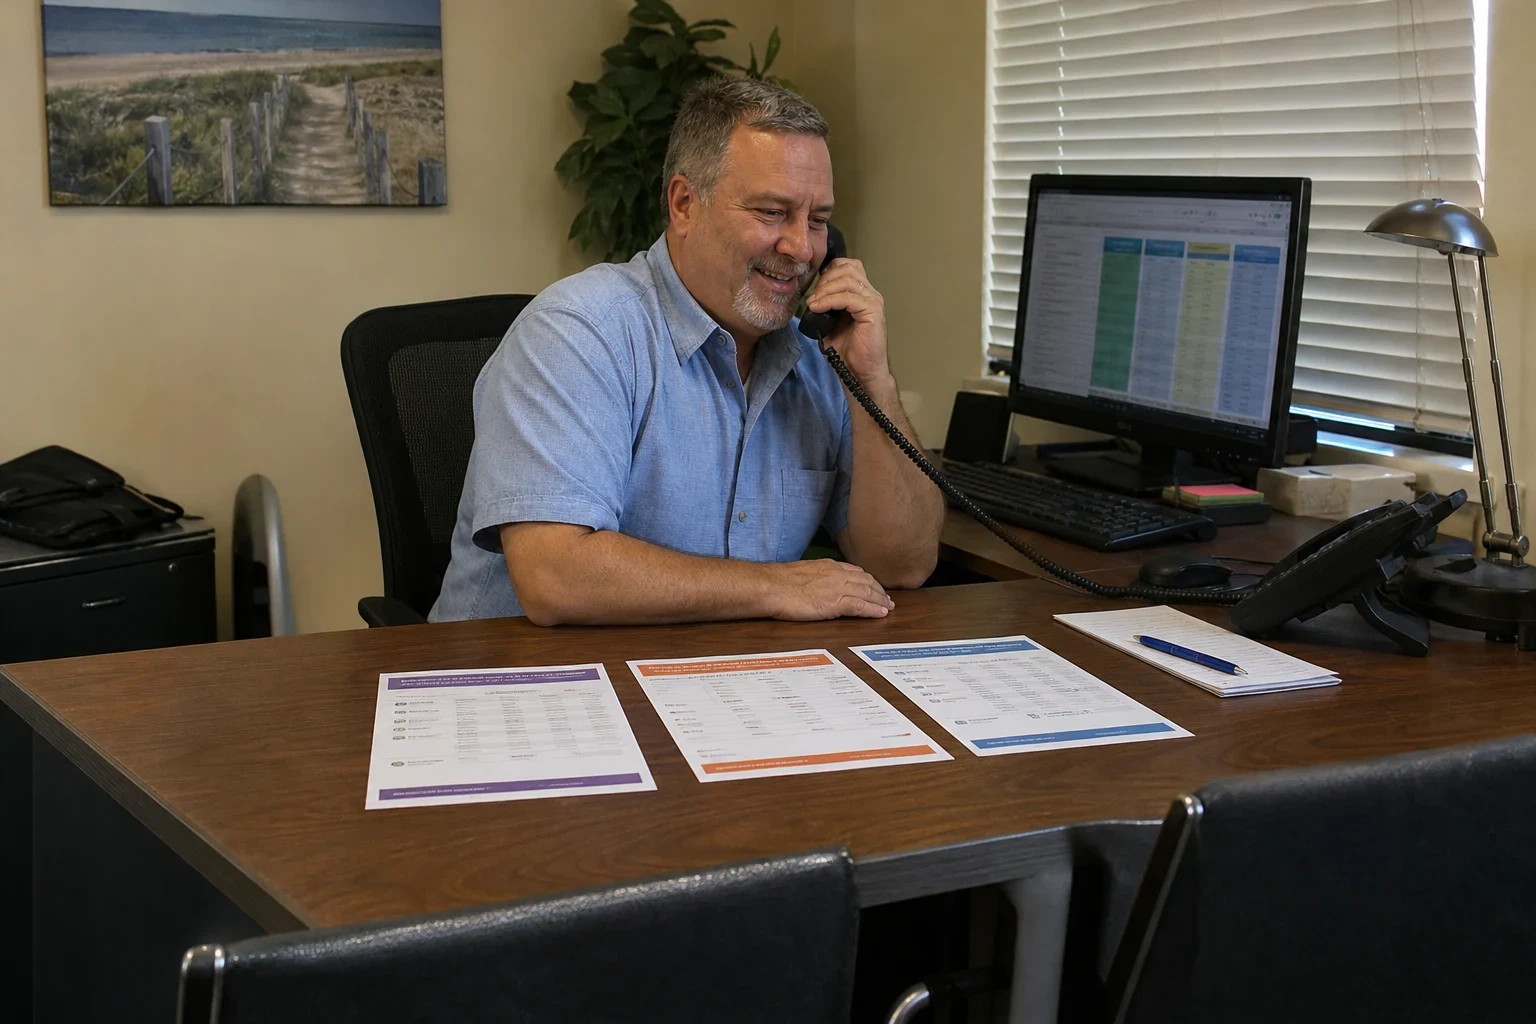
See what an injury would actually pay
We serve clients in Dunedin, Clearwater, Palm Harbor and nearby towns. One call gets you accident plans from several carriers compared on paper, with a plain explanation of how claims work.